Running a startup? Then you know as well as we do that there are about 100 different things to get done each day. You’re trying to attract new customers, secure funding, and streamline your service delivery, all with a skeleton crew.
So who could blame you for letting your books fall by the wayside? As it turns out, your future self.
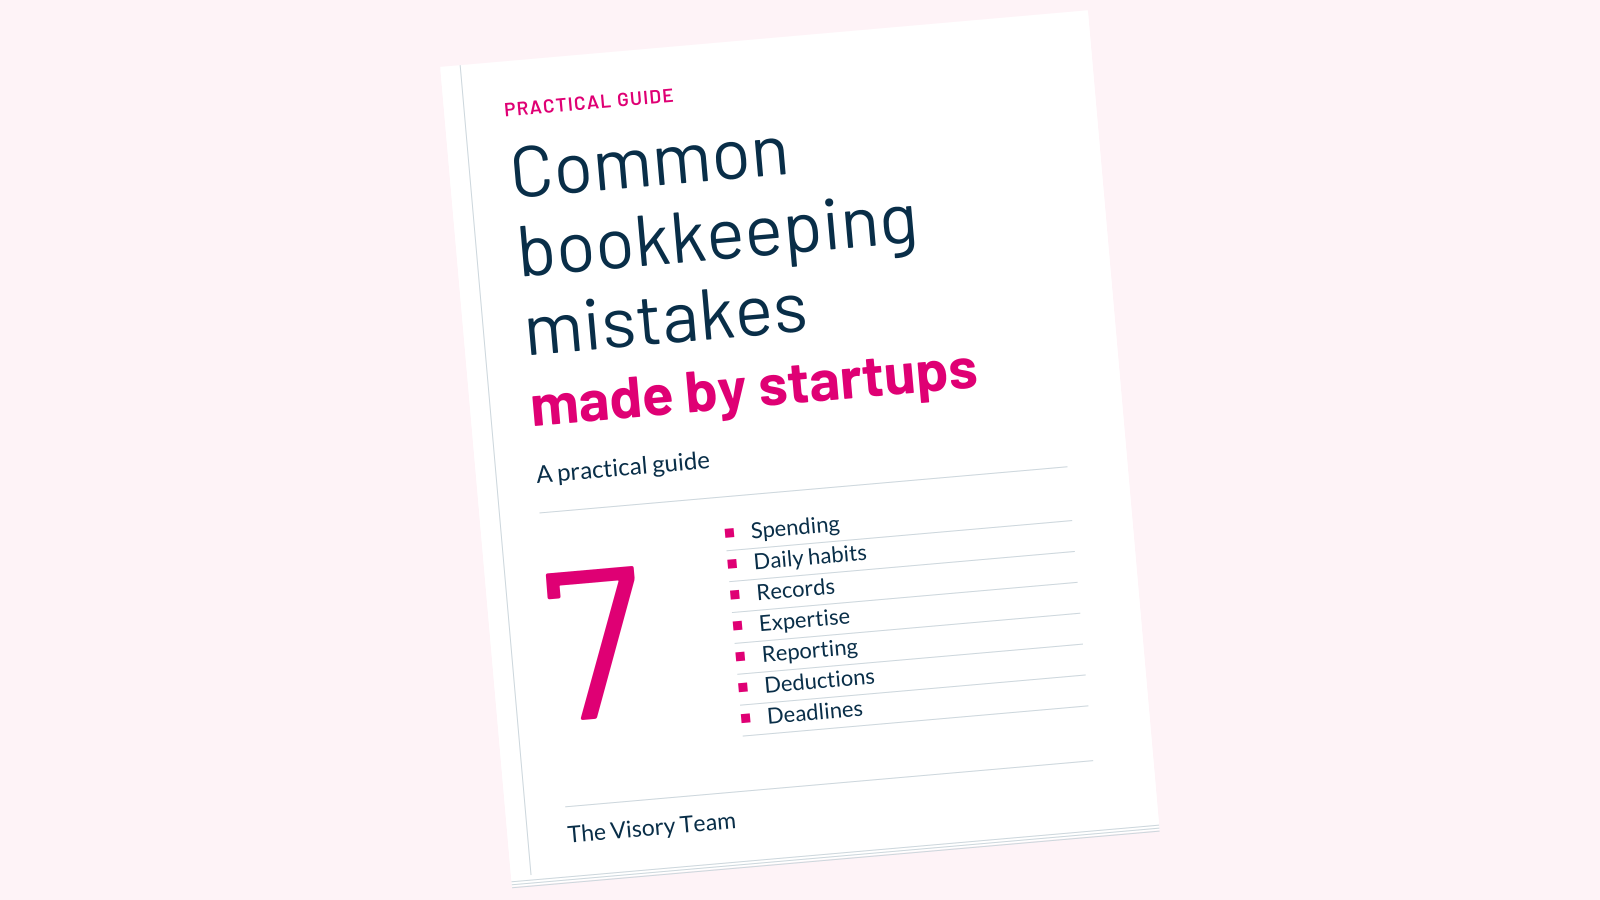
In this guide, we share the most common bookkeeping mistakes we see business owners make every year and, more importantly, how to avoid these costly errors.
7 bookkeeping mistakes you don’t want to make
-
Mixing personal and business spending
-
Continuing to put it off until you can’t stand it anymore
-
Disorganised record keeping
-
Hiring an inexperienced bookkeeper
-
Not fully understanding or reading your financial statements
-
Overlooking tax deductions
-
Missing lodgment deadlines because the books weren’t done on time
Seven bookkeeping mistakes you don’t want to make
As a bookkeeping team for startups and scale-ups, we’ve seen the same bookkeeping mistakes made over and over again. Whether you’re scaling a software business or running a services company, there are some foundational best practices that protect your company in the long run.
While avoiding these common financial mistakes might seem small, from our experience, they have a tendency to snowball. Let’s dig in.
1. Mixing personal and business spending
As a solo founder, you may end up spending your own money to get the organisation up and running. This is extremely common for a growing business. There is nothing wrong with this initially, but things get messy fast if you commingle your personal and business funds in the long run.
Everything from swiping your personal credit card to pay for a software subscription to paying office rent could bite you later, and here’s why: commingling personal and business money makes for a confusing tax situation, and a business owner can get flagged if their returns aren’t accurate. Mixing your personal and business accounts makes things messy, and even with an adviser you trust, you’ll still spend hours separating out your expenses.
According to the Australian Government, you must have a separate business bank account if you run a partnership, company, or trust. If you are operating your startup as a sole trader, you aren’t required to have a separate business account, but the government still recommends you open one.
Having a separate business bank account has a number of benefits, including:
- Making it easier to track and categorise your business expenses.
- Allowing you to create internal reports, like balance sheets and profit and loss statements, without pulling in personal expenses by accident.
- Ensuring you will have all the information you need to lodge your business taxes. You need documented proof of your expenses and income come tax time.
To separate your personal and business money, we recommend that you take these three steps:
- Open a separate business bank account with a business debit card.
- Have a business credit card that you pay off with business funds.
- Come up with a way to make sure you don’t confuse business and personal cards. Get a card from a new bank or in a totally different colour scheme so you never grab the wrong card by mistake.
2. Continuing to put it off until you can’t stand it anymore
Like going to the dentist, many startups put off their bookkeeping until it hurts. It’s tempting, but it’s not worth it. Your startup needs accounting processes in place as soon as possible.
If you put off bookkeeping until you can’t avoid it anymore, several things are likely to happen.
- You will end up paying someone to do catch-up bookkeeping. This type of bookkeeping requires someone to go back through old records, try to dig up ancient receipts, and piece together your finances with missing data. It’s better to maintain bookkeeping records as you go than try to catch up months later.
- You will have missing receipts and invoices. Over time, documents get lost. Emails get deleted. You forget things. Putting off bookkeeping is bound to make the inevitable reckoning more stressful.
- You will hate the bank reconciliation process. Reconciling your bank account with your internal records should be done monthly. Imagine having to do 12 or more months at once. No thank you.
- You may not have all necessary tax documents. To claim business expenses as deductions, you need proof of your spending. If you put off bookkeeping for too long, you may miss out on deductions because you didn’t document your spending accurately.
- You could find a mistake long after it happened. One mistake can lead to another, which leads to another, which, well, you understand. A simple accounting error could become a major headache. You want to catch errors fast.
3. Disorganised record keeping
Startups often have an organisation problem. It’s understandable, given how depleted your energy and limited your resources are. Many startups have just a handful of employees, and receipts get put into a folder until someone takes the time to sort them.
However, you will likely live to regret this way of operating. Disorganised record keeping could lead to lost documents, unpaid bills, and missing reports. If your supplier cuts you off because you don’t have an accounts payable process and you never settled your last invoice, you will wish you had streamlined sooner.
4. Hiring an inexperienced bookkeeper
Hiring an inexperienced bookkeeper may not be as bad as having no bookkeeper, but it certainly creates its own issues. An experienced bookkeeper, one with real experience working with early-stage companies, has several distinct advantages for a startup (instead of asking your cousin who is kind of good at maths).
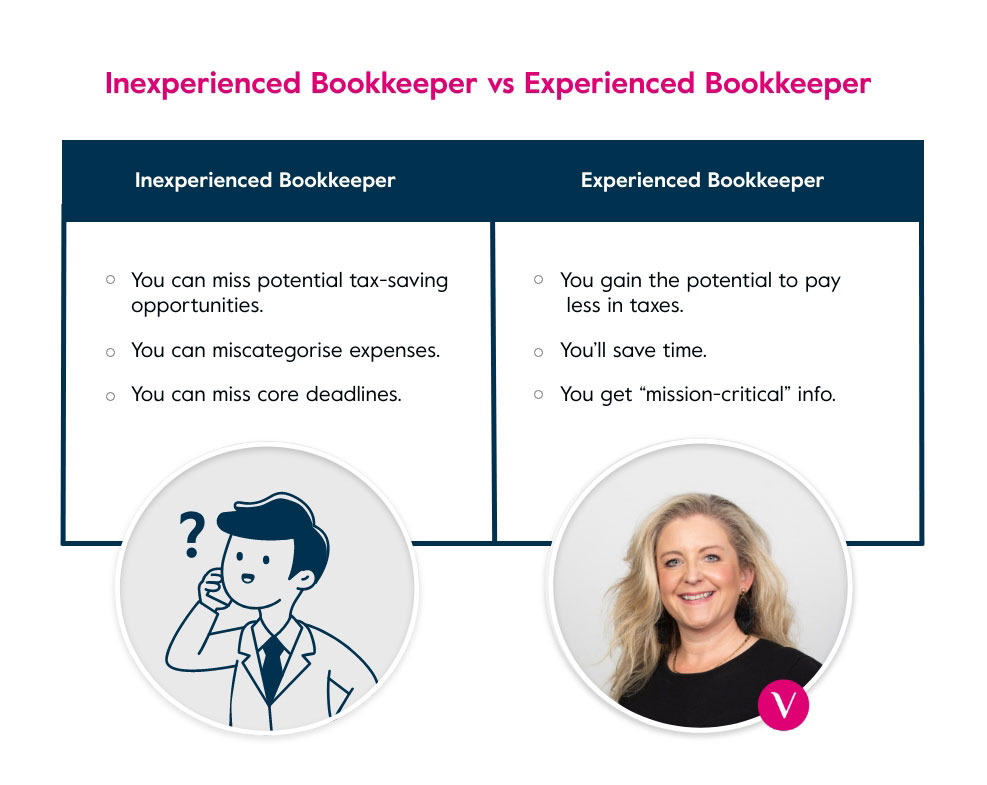
An experienced bookkeeper, who has worked with startups in your industry, will be better at:
- Preparing your Business Activity Statements (BAS), which report GST, PAYG withholding and PAYG instalments to the ATO, if the provider is a registered BAS or tax agent or works under appropriate supervision by one. Check the exact entity on the TPB register. Tax-return advice requires the relevant tax-agent authority.
- Keeping on top of your Pay As You Go (PAYG) instalments. Some startups may not earn enough to need them at first, but eventually you will need to stay on top of these instalments.
- Setting up your accounting software and structures. An inexperienced bookkeeper may not be up to date on the most modern software tools or know how to set up a secure structure for your financial documents and accounts.
- Dealing with the ATO. If you have questions about your activity statements or need a form, an experienced bookkeeper can step in and deal with the Australian Taxation Office to get things sorted. An inexperienced bookkeeper may not know where to start.
5. Not fully understanding or reading your financial statements
Financial data without analysis is just numbers on a page. If you don’t understand how to interpret your financial reports, you could make bad decisions. Worse, you may not know what essential reports you need to create for your business. Having the right documents on hand allows you to draw thoughtful insights and make informed decisions.
Some startups have the right reports being created, but they ignore them. This could mean you miss a financial error or don’t realise you’re falling into debt. It’s not just important that you generate reports, it’s also important to analyse them for insights.
Here are some of the things you should understand about your financial statements. If you’re not sure how to read them, it’s time to call in reinforcements.
- Reading a balance sheet. Your balance sheet tracks your assets, liabilities, and equity (including owner equity). Your assets are equal to your liabilities plus your equity. The two sides of the report should even out.
- Reconciling bank statements. Your bank balance and reported transactions should match what your internal reports say you’ve been spending. You or your bookkeeper should check monthly to see if there are discrepancies, such as missing money you can’t account for.
- Looking over profit and loss statements. Also called an income statement, this important document can tell you how much you spent and how much you earned in a particular time period. You should be able to analyse it and understand if you are overspending or if you have redundant expenditures.
- Reading your accounts receivable and accounts payable reports. Trade receivables track what customers owe for goods or services; trade payables track what you owe suppliers. Borrowed money creates cash and a loan payable, not sales income or a trade receivable. You should be able to understand how to track these reports and what the process is to make sure you get paid on time and pay your bills on time.
6. Overlooking tax deductions
Tax deductions are expenses you paid for your business that can offset your tax burden. In other words, by claiming business expenses, you may lower your tax bill. Overlooking deductions is often an expensive mistake.
Tax deductions can get complicated. From claiming the wrong items to missing a deduction or timeline, you could wind up paying more tax than you need to. At Visory, there are three important rules we keep in mind when looking for tax deductions.
According to the Australian Government, for an expense to qualify as a tax deduction, it must meet all three of these rules:
- The expense you are claiming must have been for business use, not private use. Don’t try to slide in a personal mobile phone as a business expense. You can only claim it if you use it to run your business.
- When an expense is related to both business and private use, you can only claim the business portion. If you use a vehicle for work 50% of the time and personal leisure 50% of the time, you can’t claim the entire car on your business taxes. Under an eligible actual-cost method, a substantiated 50% business-use share applies to eligible running costs and decline in value, not automatically to half the purchase price. If eligible annual decline in value is $8,000, 50% business use gives a $4,000 deduction. If the business is a company, the car costs are generally deductible in full and private use by directors or staff is dealt with through fringe benefits tax or Division 7A instead. The available method depends on the entity and vehicle; confirm it with your tax agent.
- You must have adequate records to prove where your expenses went. It’s not enough to tell the ATO your startup spent $5,000 on new laptops. You must have the receipts. Failing to keep proper records will likely result in your deduction being denied. Document, document, document.
At the end of the day, you may be able to deduct more expenses than you think. For instance, companies can deduct supplies they use to keep their premises hygienic, such as hand sanitiser in the bathrooms and protective gear for staff who deal with the public.
7. Missing lodgment deadlines because the books weren’t done on time
The ATO sets a due date for every tax return and activity statement, and the dates depend on the type of entity and whether a registered tax agent lodges for you. If you don’t lodge on time, you could be subject to a failure to lodge on time (FTL) penalty.
The ATO generally doesn’t apply penalties in isolated cases of late lodgment, and it warns you before it does. However, it reserves the right to apply them, and we’ve certainly seen that happen. The base penalty is one penalty unit for every 28 days (or part of 28 days) that a document is overdue, up to a maximum of five units, and it is multiplied by two for medium entities and by five for large entities, judged on withholder status or GST turnover.
In addition to your annual tax return, keep in mind that you may be responsible for activity statements during the year, and most investors will want periodic reports about your financial health. The more organised you are with your monthly bookkeeping, the easier it is to pull these reports and lodge on time.
The main takeaways
Between conversations with investors, validating your idea, winning new customers, building your team and reviewing term sheets, running a startup is a tricky balancing act. In our experience, it’s easy to see why some companies don’t collect the financial data they should, and often ignore data when they should analyse it. There is a lot to get done and only so much time in the day. A lot of problems boil down to overwhelmed small businesses not having the time or expertise to take care of their books properly.
If you are struggling to keep accurate books, Visory can help. A dedicated team you know by name runs your bookkeeping every month, and your Business Performance Partner walks you through what the numbers mean, long before you are ready for a CFO.
About this guide
Written by The Visory Team. Published . General information for Australian businesses, not advice for your situation.